Introduction
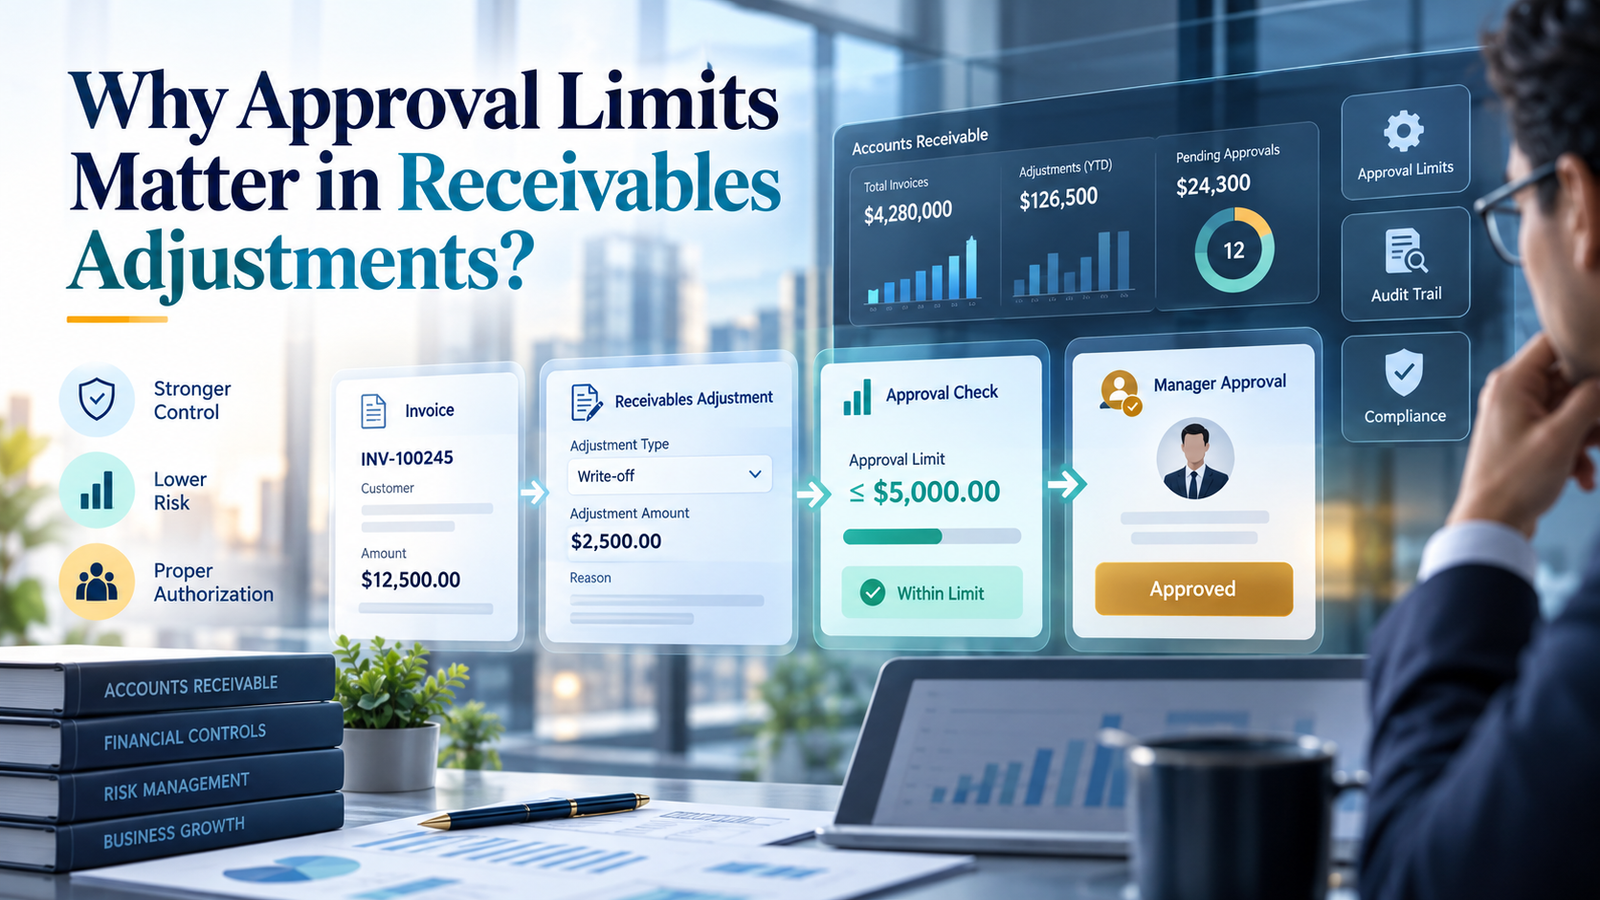
Receivables adjustments change what a customer owes and what an organization recognizes in its books, so approval cannot rest on general system access alone. As Tech Leads IT often emphasizes in its Oracle Fusion Financials Training sessions, an approval limit is a decision boundary tied to a specific activity, amount range, and currency, not a blanket permission. This lets routine corrections move quickly while stopping any one operator from holding unchecked authority over every outcome. Without it, valid adjustments stall while riskier ones slip through unchecked.
An approval limit isn’t about friction; it separates preparing a transaction from authorizing it. Learners in a well-structured Oracle Fusion Financials Online Training program, or any solid Oracle Fusion Financials Course, see how a properly configured limit makes that separation visible, giving reviewers a consistent basis for deciding what proceeds and what escalates.
Oracle Fusion Financials Training and the Principle That Approval Authority Is Specific, Not Universal
A workable approval model has to answer three questions before any adjustment is submitted: What kind of document or activity is involved? What amount of money can this particular person approve? And which currency does that range apply to? This is one of the first distinctions covered in structured Oracle Fusion Financials Training, because it’s easy to assume that authority granted for one type of transaction should carry over to a related one and that assumption is exactly where control gaps appear. Authority to approve an adjustment in one currency does not automatically extend to another currency, and authority over adjustments does not imply authority over write-offs or credit memos. Each combination of activity, amount, and currency needs to be evaluated on its own terms.
This specificity is what makes accountability traceable later on. If an adjustment falls inside a user’s configured range, that user is acting under a clearly defined delegation, and there is a record of exactly why the transaction moved forward. If it falls outside that range, the system should not let the transaction quietly borrow authority from a job title, a manager’s general access, or a “we’ve always done it this way” team convention. Instead, the transaction state should make it obvious that a further decision is required. This lets managers review the actual financial event on its merits rather than trying to reconstruct informal permissions after the fact from email threads or verbal agreements.
How an Oracle Fusion Financials Online Training Program Frames Configuration as the Foundation of Policy
Approval limits don’t operate in isolation; they sit inside a larger receivables configuration, and this is where an Oracle Fusion Financials Online Training path adds real value, because it shows how each configuration layer supports the next. System options establish the overall operating environment. Receivables activities determine how items such as adjustments and write-offs are accounted for. Automatic accounting rules decide which accounts a transaction defaults to. Receipt classes and methods govern how payments are processed in the first place. Approval limits sit on top of all of this as the human authority layer, the piece that decides who is allowed to make which decision, within the structure that the rest of the configuration has already established.
If the underlying activity setup and accounting rules are ambiguous or inconsistent, even a perfectly calibrated approval threshold won’t make the resulting transaction easy to interpret later. The Oracle Help Center’s guidance on configuring receivables for operational use lists approval limits as one of the required configurations for a functioning receivables environment, and it specifically ties them to whether a user can approve adjustments or credit memo requests. That framing matters: approval design is an implementation-stage decision, not something to patch together after users start hitting blocked transactions in production. Limits need to be defined alongside the activities they govern, and tested thoroughly before those activities become part of daily processing.
Reading Pending Status as a Control Signal, Not a System Problem
When an adjustment falls outside a user’s approval range, the resulting pending status is genuinely useful information rather than an inconvenience to route around. It tells the organization that the transaction has been recorded but hasn’t yet received the authority it needs to proceed. Teams responsible for daily operations should treat that pending state as a queue that needs active ownership, someone checking it, working it, and clearing it not as a workaround waiting to happen. The person reviewing a pending item needs several things in front of them: the customer context, the stated reason for the adjustment, any supporting documentation, the proposed accounting effect, and a clear explanation of why the amount couldn’t be resolved through a normal receipt application or a standard transaction correction.
A weak process allows pending items to age in a queue without ever distinguishing between two very different causes: missing evidence and unavailable authority. A stronger process separates them immediately. If the evidence is incomplete, the item goes back to whoever prepared it. If the amount simply exceeds the preparer’s configured range, it moves up to someone with the right authority. If the adjustment itself turns out to be inappropriate, it gets rejected with a documented reason that feeds into later analysis. Clear, distinct outcomes like these prevent the same item from being resubmitted repeatedly, and they preserve the important difference between a workflow delay and an actual financial disagreement that needs resolving.
Why an Oracle Fusion Financials Course Treats Different Receivables Activities as Different Risk Categories
Receivables actions can look superficially similar to each other while carrying very different controls underneath, and this is a point that any well-structured Oracle Fusion Financials Course spends real time on. An invoice adjustment changes an open balance. A receipt write-off addresses an unapplied amount or an underpayment. A credit memo refund returns value tied to an existing on-account credit. Keeping these as separate document types lets the approval model reflect the real differences between them, rather than flattening them into a single generic “adjustment” category.
Reusing one broad approval threshold across all of these activities might look administratively simpler on paper, but it tends to obscure the fact that each action has its own cause, its own supporting evidence requirements, and its own effect on cash position or customer balance. Receipt write-offs deserve particular attention here, because user-level approval limits operate alongside separate write-off amount limits set in receivables system options. A user’s individual limit is not a way to bypass that broader system-level boundary both layers need to hold at the same time. This layered structure reflects a useful design principle worth internalizing: global system settings define what the environment permits overall, while individual approval limits define who, specifically, may act within that permitted space. Testing needs to cover both layers together, including transaction amounts that sit just inside and just outside each boundary.
Testing the Edges Before Users Find Them the Hard Way
The most revealing test cases sit right at the edges of a configured range: the lower limit, the upper limit, one unit below each, and one unit above each. These tests should be repeated across every relevant currency and every relevant document type, because a limit that behaves correctly in one currency won’t necessarily behave correctly when copied over to another. Testing also needs at least two users configured with different authority levels, so the team can actually observe the full lifecycle submission, pending status, approval, and rejection rather than just confirming that one happy path works.
A single successful adjustment only proves that one path functions correctly; it says nothing about whether the boundary actually prevents an unauthorized decision, or whether an out-of-range transaction gets routed to the right exception path. Negative testing matters just as much as positive testing here. A user without a configured range for a given activity should never end up acquiring authority through some unrelated responsibility or role assignment, and a transaction submitted in the wrong currency should never get approved against a threshold that happens to be convenient locally. Recording both the expected and the actual status at every step of these tests turns them into reusable evidence something the team can refer back to later whenever roles change, limits are adjusted, or new activities are added to the configuration.
Reviewing Patterns, Not Just Individual Transactions
Once limits are live, operational review should shift from individual transactions to patterns across the whole queue. A cluster of pending items sitting just above one particular threshold might mean that a user’s authority no longer matches the normal size of the transactions they handle or it might point to a recurring upstream error that’s inflating amounts before they even reach the approval stage. Frequent rejections tied to the same underlying reason often signal that adjustment guidance for preparers isn’t clear enough, rather than that the limit itself is wrong.
The default response to friction shouldn’t automatically be to raise the limit. Instead, owners should look closely at what’s actually causing the transactions, how strong the supporting evidence tends to be, how long items are sitting in the queue, and whether pending items are concentrated around particular users or activities before making any change to the delegation structure itself.
Conclusion
Approval limits do their job well when they express real organizational responsibility in system terms tied to a specific activity, a specific amount range, a specific currency, and a named individual with clear authority. They keep the act of entering a transaction separate from the act of authorizing it, they make out-of-range decisions visible rather than invisible, and they give pending work a controlled, traceable path to resolution. Well-designed Oracle Fusion Financials Online Training should connect configuration decisions directly to the daily review queue, showing learners exactly how approval limits interact with document types and system-level options in practice. A strong Oracle Fusion Financials Training program takes this further, reinforcing that the goal isn’t simply faster approvals, it’s a decision trail that still makes sense to someone reviewing it long after the adjustment itself has been completed.
Why Approval Limits Matter in Receivables Adjustments?