
Introduction
Picture a department manager who checks the budget report on the 20th and sees plenty of money left. Two weeks later, finance tells her she’s over. Tech Leads IT designs its Oracle Cloud Financials Training around exactly this kind of gap. The report showed only what had reached the ledger and missed the requisitions and purchase orders already in motion.
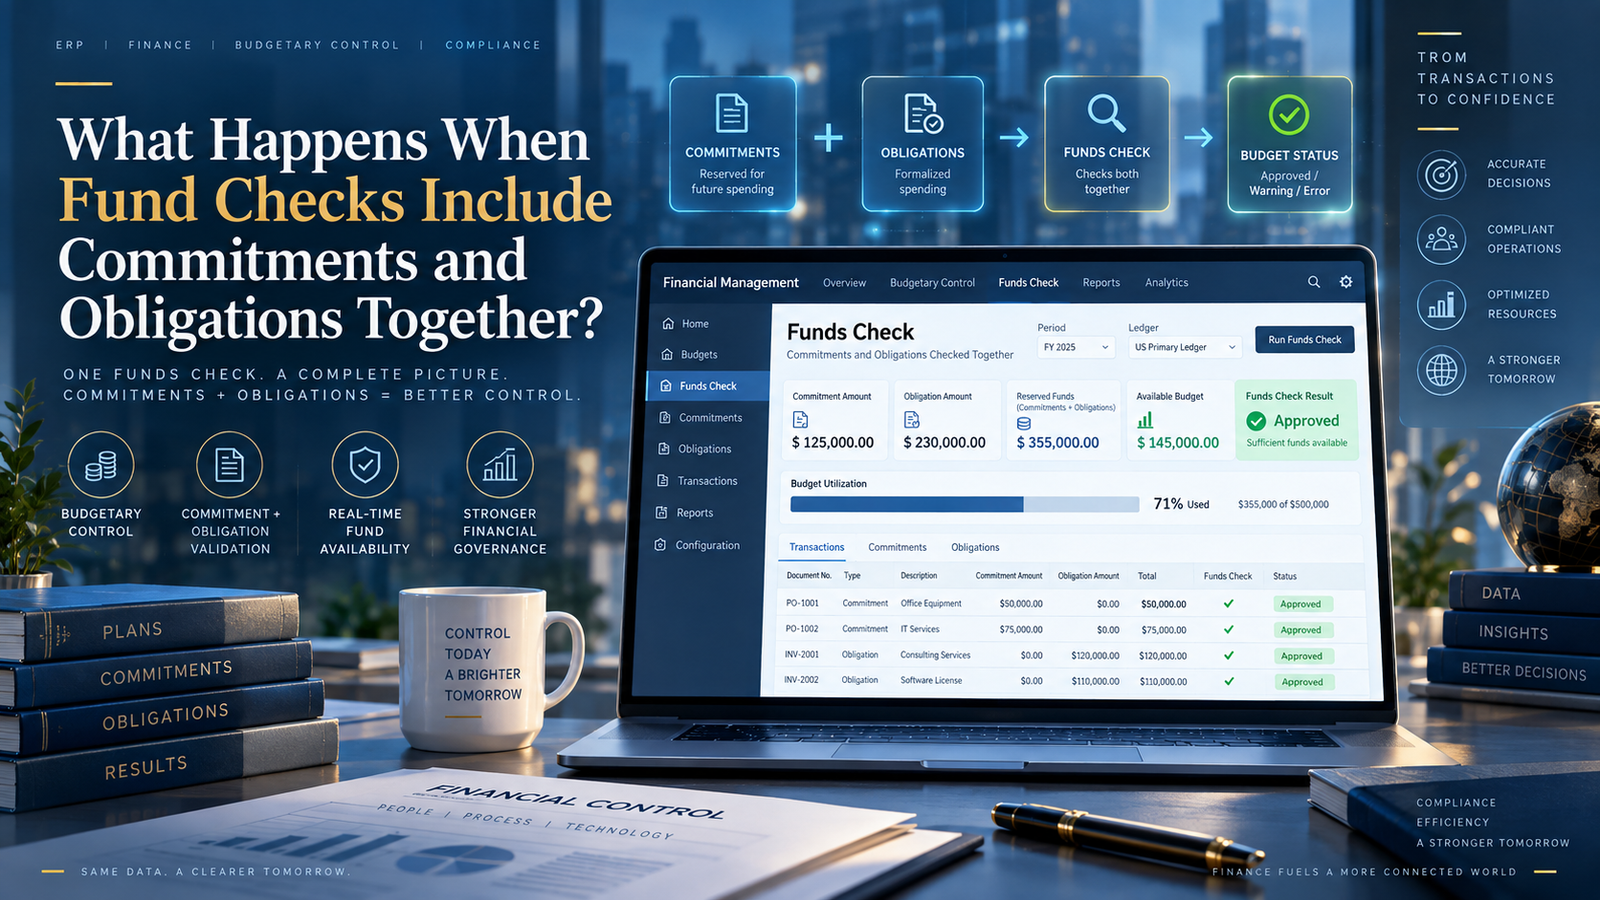
Budgetary control closes that gap by checking spending documents against control budgets while they’re still intentions, recording their effect as commitments, obligations, or expenditures. Finance gets a warning while there’s still time to act. With Oracle Cloud Financials Training Online from Tech Leads IT, learners practice this full cycle hands-on, from the first requisition to the final expenditure.
Why Early Visibility Matters in Oracle Cloud Financials Training
A requisition isn’t an expense, and nobody should treat it like one. But it isn’t nothing either. When someone asks to buy something, a slice of the budget is spoken for, and budgetary control captures that. A requisition may reserve funds as a commitment. Once it becomes an approved purchase order, the amount moves to an obligation and the earlier commitment is relieved. Receipts and invoices then carry it toward actual expenditure. The exact events depend on which applications you’ve enabled and how they’re set up, but the logic holds up everywhere.
Good Oracle Cloud Financials Training puts this staged thinking up front, because everything else builds on it. If you can explain why a requisition affects available funds before any invoice exists, you can explain most funds-check results to a puzzled requester. That skill matters far more than knowing which menu holds which setup screen.
The Control Budget Decides What You See
Budgetary control doesn’t check against a spreadsheet total someone keeps on the side. It checks against a control budget, which defines the budget being controlled, its calendar and periods, its currency, its control level, and the account or segment structure used to evaluate transactions. Those choices set how detailed the check gets. A healthy total at a high level can easily hide a shortage in one department, one cost center, or one account combination. So before you read a pass or a failure, ask what exactly the system was checking.
The control level matters just as much. Depending on setup, the system might block a transaction when funds run short, show an advisory message, or quietly track consumption without stopping anything. Requesters often misread these results. A passed check only means the transaction met the applicable controls at that moment. It doesn’t mean the purchase is a good idea. And a warning isn’t automatically a glitch. Sometimes it’s the system doing its job, flagging that a request crossed a monitored threshold so someone authorized can decide what happens next.
Commitments and Obligations Show the Pipeline
Actual-versus-budget reporting only tells you the story after accounting catches up. Commitments and obligations fill in what’s still coming. Take a department with a 500,000 budget, 320,000 in actual expenditures, 40,000 in open commitments, and 110,000 in obligations. Actuals alone suggest 180,000 is available. Once you count the pipeline, only 30,000 is. That’s a very different conversation, and the sooner finance has it, the better.
The balances also tell you where spending is sitting. A big commitment balance might mean requisitions are stuck waiting for approval. A big obligation balance might mean purchase orders are open and nobody has received the goods or matched an invoice. Neither proves a mistake, though. They’re prompts for questions. Is that requisition still needed? Should the order be reduced or canceled? Is an invoice overdue, or did the supplier never bill us? Asked regularly, those questions turn budget monitoring from a look in the rearview mirror into ongoing management of purchasing.
Funds Checks Are Smarter Than a Balance Lookup
It’s tempting to think a funds check just compares an amount to a remaining balance. In practice it looks at each transaction distribution against the right control budget and period, using your budgetary control setup. The account combination, amount, date, currency treatment, and document status all play a part. A purchase order with five distributions can pass on four and fail on one, so don’t stop at the header total. Open the distribution-level results and read them.
There’s another distinction people trip over: checking funds versus reserving them. A check can tell you whether money is available without leaving the same lasting mark on the budget that a completed reservation does. Keep that in mind when a requester swears the funds were there. Compare the budget date, control budget, account, and consumption type on the transaction with whatever inquiry they used. Often they were looking at a different period, a parent value, a broader budget, or an actuals-only view, while the funds check was also counting reservations already in place. Oracle’s product documentation covers the concepts well, but read it next to your own control-budget design, since your local choices determine what gets controlled.
Following a Document Through Its Lifecycle
Early visibility only helps if the numbers stay right as documents change. When a requisition becomes a purchase order, the earlier commitment is liquidated as the obligation is recognized, so the same money isn’t counted twice. Later, obligations are liquidated as expenditures appear. Changes, cancellations, rejections, returns, and final closes can all shift what’s still reserved. So don’t add up every balance on screen as if each were separate. Trace the related documents together and ask which earlier amount each new event replaced.
Dates make this trickier than it looks. A requisition might reserve funds in one budget period while the purchase order or invoice lands in a later one. Period status, budget rules, and document changes all affect where consumption shows up. Year end is where this bites. Teams need to list open commitments and obligations, work out which are still legitimate, and use the supported carry-forward, cancellation, or close procedures that fit their policy. Leave stale documents open and you understate what’s really available. Clear them out without checking with the owner and you might free up money that an active purchase still needs.
When a Funds Check Fails, Treat It as a Clue
A failed or warned funds check deserves the same care as any accounting exception. Write down the document and distribution, budget date, account, amount, currency, control budget, control level, and the exact message. Then look at what’s consuming the available funds: the budget itself, adjustments, commitments, obligations, expenditures, and other reservations. Usually the cause turns out to be one of a handful of things. There may be a real shortage, a coding error, an unexpected date, a stale reservation, or a budget change that never finished its approval process. Each of those points to a different owner, so figuring out which one you have saves everyone a lot of back and forth.
How you resolve it matters too, because the audit trail should tell a clear story. A requester can fix a miscoded line. Procurement can close or shrink an order nobody needs anymore. Budget staff can approve a transfer or adjustment. Where policy allows it, an authorized exception may be the right route. What you shouldn’t do is bump up the budget just to make a transaction pass, because that hides the actual decision. Afterward, rerun the check or reservation and confirm both the transaction result and the updated balance. Otherwise you’ve only moved the warning somewhere else.
Picking Oracle Cloud Financials Training Online That Actually Prepares You
Budgetary control is one of those topics you can’t learn by reading alone. You need to click through it. That’s a big reason working finance professionals and career switchers look at Oracle Cloud Financials Training Online, since it lets them practice on their own schedule. A good program walks you through the whole cycle: set up a control budget, raise a requisition, watch the commitment appear, convert it to a purchase order, and follow the liquidation through to expenditure. After a few rounds, you start reading balances in context without thinking about it.
When you compare courses, look past the syllabus. Ask whether the labs include a funds check that passes on one distribution and fails on another, dates that straddle two budget periods, and stale reservations that need sorting out before year end. Those are the situations you’ll hit on the job. A course that teaches you to weigh a budget-control decision, rather than just report a pass or fail, is worth more than one that only lists the features.
Conclusion
Budgetary control lets finance see spending earlier by tying proposed and ordered activity to controlled budget balances before anything reaches the ledger as an actual. Commitments and obligations reveal the pipeline, funds checks test each distribution at the configured control level, and liquidation links one stage to the next.
The teams that get the most from it read results in the context of the document, watch open reservations, and settle exceptions through decisions someone owns. Whether you learn this on the job or through Oracle Cloud Financials Online Training, the aim is the same: turn early warnings into better spending decisions. For hands-on practice at your own pace, Oracle Cloud Financials Training Online can help you build that judgment.