
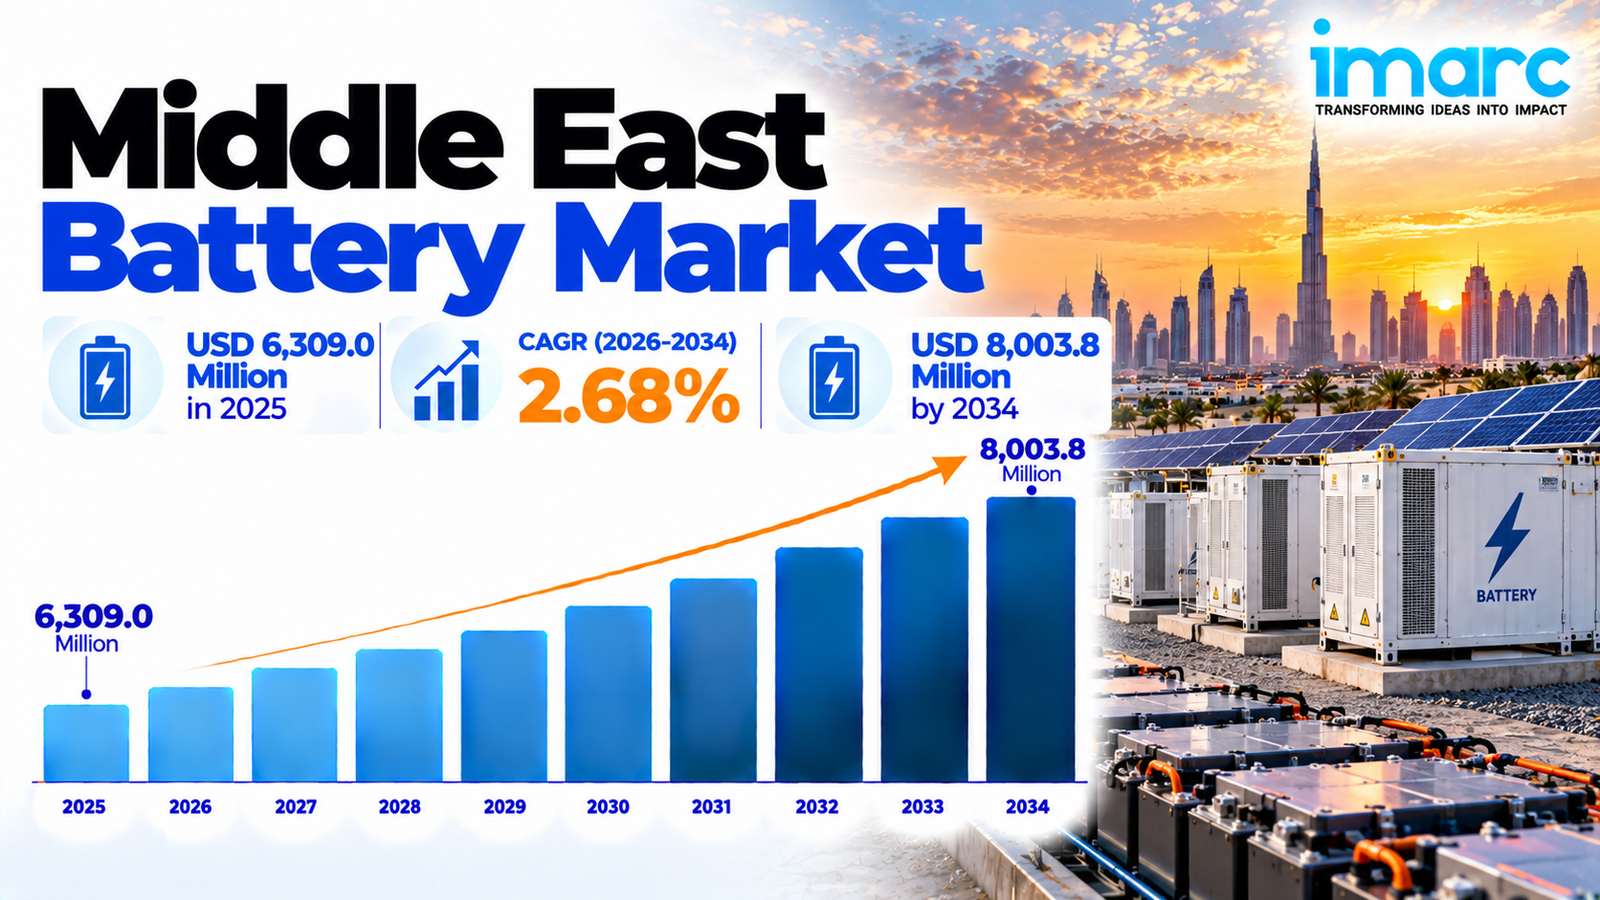
The Middle East battery market size reached USD 6,309.0 Million in 2025 and is projected to touch USD 8,003.8 Million by 2034, growing at a CAGR of 2.68 percent during 2026-2034. The region’s accelerating pivot toward sustainable power sources, the steady spread of connected devices across homes and industrial facilities, and a growing appetite for large-scale energy storage installations are among the central forces pushing the market forward. As national utilities across the Gulf roll out multi-gigawatt-hour storage programs and transport networks electrify, demand for both primary and rechargeable battery chemistries is widening across automotive, industrial, and portable use cases.
Government-backed clean energy agendas in Saudi Arabia, the UAE, and neighboring markets are reshaping how power is generated, stored, and distributed, and batteries sit at the center of that shift. Utilities are moving from pilot-scale storage to gigawatt-class deployments, while automakers and device manufacturers lean more heavily on lithium-ion chemistries for range, charging speed, and compact form factors. Together, these forces are setting the stage for steady, broad-based growth across the region’s battery value chain through 2034.
Market at a Glance
- Market Size (2025): USD 6,309.0 Million
- Market Forecast (2034): USD 8,003.8 Million
- Growth Rate (2026-2034): CAGR of 2.68%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Segments Covered: Type, Product, Application, and Country
- Countries Covered: Saudi Arabia, Turkey, Israel, UAE, Iran, Iraq, Qatar, Kuwait, Oman, Jordan, Bahrain, and Others
How AI is Reshaping the Future
- AI-enabled battery management systems are improving charge-discharge efficiency, extending cell life, and giving operators real-time visibility into the health of large storage installations.
- Machine learning models are speeding up materials discovery, helping manufacturers test new electrode chemistries and electrolyte formulations faster than traditional lab-based methods allow.
- Predictive analytics are reducing unplanned downtime in industrial and grid-scale applications by flagging degradation patterns before cells fail, lowering maintenance costs for operators.
Grab a sample PDF of this report: https://www.imarcgroup.com/middle-east-battery-market/requestsample
Market Trends and Drivers
The clearest driver behind the region’s battery demand is the broader move away from fossil-fuel-dependent power generation. As Gulf utilities expand solar and wind capacity, batteries have become essential to smoothing out supply, storing surplus generation during peak sunlight or wind hours, and releasing it when demand climbs. National programs across Saudi Arabia and the UAE are now commissioning battery energy storage projects measured in gigawatt-hours rather than megawatt-hours, a scale shift that is pulling in both global cell suppliers and regional assembly partners and lifting demand for secondary, rechargeable battery chemistries in particular.
Parallel to the energy storage buildout, transport electrification is opening a second major growth channel. Regional governments are setting targets to cut vehicle emissions and encourage electric mobility, which is translating into stronger demand for lithium-ion batteries offering higher energy density, quicker charging, and longer service life. At the same time, the steady proliferation of connected devices, from smart home equipment to industrial sensors and monitoring systems, is sustaining demand for compact, long-lasting portable batteries across both consumer and enterprise settings.
Sustainability concerns are also beginning to influence how the market operates further down the value chain. Rising scrutiny of battery disposal practices is pushing manufacturers to explore alternative materials and designs with a smaller ecological footprint, while some players are adopting circular-economy practices that prioritize recycling and the repurposing of battery components. Interest in solid-state battery technology is climbing as well, given its potential for higher energy density and improved safety, pointing to a market that is maturing technologically even as its core growth drivers remain firmly in place.
Government Initiatives and Regional Industrial Policies Driving Demand
- Saudi Arabia’s national utility has commissioned a 2.5 GW, 12.5 GWh grid-scale battery storage programme spanning five regions, one of the largest deployments of its kind worldwide, as part of a broader plan to procure up to 10 GW of battery storage capacity by 2030.
- The UAE’s Masdar and Emirates Water and Electricity Company have advanced a 5.2 GW solar plus 19 GWh battery storage scheme in Abu Dhabi, positioned as one of the world’s first gigascale round-the-clock renewable energy projects.
- Wider Gulf net-zero and Vision 2030-aligned energy diversification agendas continue to steer utility-scale tenders and incentives toward battery storage, reinforcing a policy backdrop that favors sustained investment in the sector.
Middle East Battery Market Segmentation
Breakup By Type:
- Primary Battery
- Secondary Battery
Secondary, rechargeable batteries are seeing the stronger pull from the region’s storage and electrification programs, given their ability to be cycled repeatedly in grid and automotive applications, while primary batteries continue to serve steady, replacement-driven demand in portable and low-drain devices.
Breakup By Product:
- Lithium-Ion
- Lead Acid
- Nickel Metal Hydride
- Nickel Cadmium
- Others
Lithium-ion chemistries are gaining the most momentum given their relevance to electric mobility and large-format storage, while lead-acid batteries retain a solid base in uninterruptible power supply and automotive starter applications. Nickel metal hydride and nickel cadmium chemistries continue to find use in select industrial and specialty device applications where their specific performance characteristics are valued.
Breakup By Application:
- Automotive Batteries
- Industrial Batteries
- Portable Batteries
Automotive applications are benefiting from the region’s push toward electric and hybrid vehicles, industrial applications are expanding alongside grid storage and backup power installations, and portable batteries continue to track the growth of connected consumer and enterprise devices.
Breakup By Country:
- Saudi Arabia
- Turkey
- Israel
- United Arab Emirates
- Iran
- Iraq
- Qatar
- Kuwait
- Oman
- Jordan
- Bahrain
- Others
Saudi Arabia and the UAE are emerging as the region’s most active battery markets, underpinned by gigawatt-scale storage tenders and electric-mobility targets, while Turkey and Israel contribute meaningful demand through their broader industrial and technology sectors. The remaining Gulf and Levant markets are expected to grow steadily as national energy diversification plans mature.
Competitive Landscape
- BYD Energy Storage
- Panasonic Holdings Corporation
- EnerSys
- Exide Industries Ltd.
- Middle East Battery Company (MEBCO)
- East Penn Manufacturing Co.
What Does The Full Report Cover
The complete Middle East battery market report builds on the themes outlined above with a detailed, data-backed assessment of historical performance from 2020 through 2025 and a forecast running through 2034. It breaks the market down by type, product, application, and country, maps the competitive landscape and strategies of leading players, and applies Porter’s Five Forces to gauge the intensity of competitive rivalry, supplier and buyer power, and the threat of new entrants and substitutes.
Recent News and Developments
- June 2026: Saudi Energy commissioned a 2.5 GW, 12.5 GWh grid-scale battery storage programme across five regions, built with Alfanar Company and BYD Energy Storage, described as the world’s largest deployment of its kind.
- January 2026: Masdar and Emirates Water and Electricity Company reached financial close on their 5.2 GW solar and 19 GWh battery storage project in Abu Dhabi, with BYD Energy Storage securing an 11.275 GWh battery supply contract for the scheme.
- April 2026: Saudi Arabia moved to tender a 2 GW battery storage project, the first phase of a plan to procure up to 10 GW of battery energy storage capacity by 2030.
Note: The report can be customized to meet your specific requirements, including additional segments, countries, or a deeper focus on any particular area of the Middle East battery market.
Key Questions Answered in This Report
- How has the Middle East battery market performed so far, and how will it perform in the coming years?
- What is the breakup of the Middle East battery market by type, product, and application?
- What are the key drivers and challenges shaping the Middle East battery market?
- Who are the key players in the market, and what is the degree of competition?
- What are the various stages in the value chain of the Middle East battery market?
Why Choose IMARC?
IMARC Group is a leading market research company that offers management strategy and market research worldwide. We partner with clients across industries and geographies to identify their highest-value opportunities, address their most critical challenges, and transform their businesses.
- IMARC’s information products include major market, scientific, economic and technological developments for business leaders in pharmaceutical, industrial, and high-technology organizations.
- Our offerings include comprehensive market intelligence in the form of research reports, production cost reports, feasibility studies, and consulting services.
- Our team consists of experienced professionals, including analysts, researchers, and industry experts skilled in various areas of the market research industry, including market sizing, forecasting, competitive analysis, and data visualization.
Contact Us
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-631-791-1145