Introduction
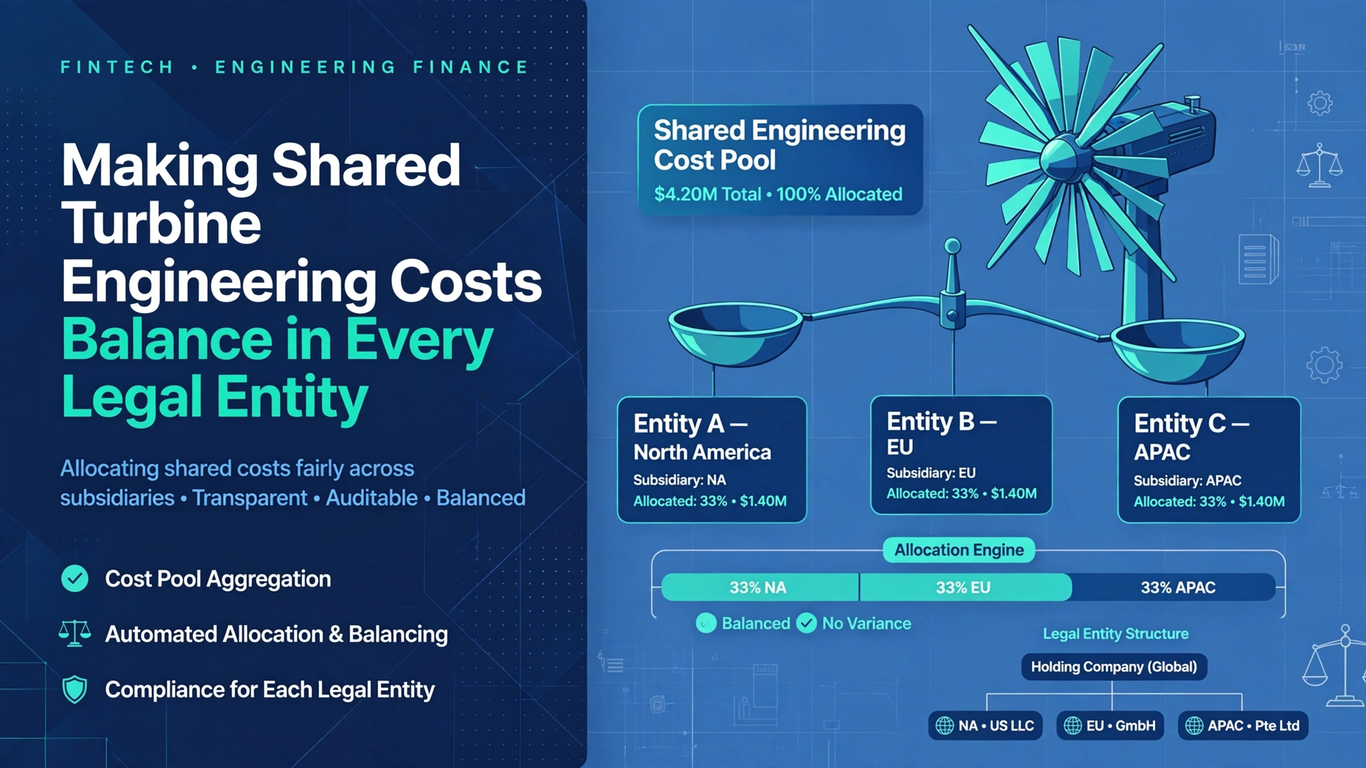
A Danish engineering centre designs turbine blades all year, then passes the costs to wind-farm companies in Poland and Portugal. At Tech Leads IT, we use this example in our Oracle Fusion Financials Training because the journal can balance in total yet stay out of balance by legal entity.
A group accountant cannot judge it by the grand total. She must know who supplied the engineering, who received it, and which receivable and payable accounts should result. Whether you join an Oracle Fusion Financials Online Training batch or follow an Oracle Fusion Financials Course, the goal is defensible counterparty positions.
Oracle Fusion Financials Training Begins With the Economic Story
Before anyone opens a rule screen, write down what actually happened. The cost schedule starts with the engineers’ approved project charges and the allocation basis the group has adopted. It names the Danish provider, the Polish and Portuguese receivers, and the amount assigned to each. It also records the journal source and category, the ledger, and the balancing values involved. Local controllers confirm that the receiving entities are the right ones and that nobody is using the allocation to patch an unrelated variance.
This schedule becomes your expected result, and every generated balancing line gets tested against it. Skip it and you invite a quiet trap: the due-to and due-from lines the system creates look convincing, so they get accepted even when the distribution underneath them is wrong.
Now take the example. The journal credits engineering expense recovery in Denmark and debits engineering expenses in Poland and Portugal. In total it balances, but the three company positions do not. The expected bridge should show an intercompany receivable in Denmark and an intercompany payable in each receiver, with counterparties and totals that mirror the allocations exactly.
Roles matter here too. The chart architect maps legal entities to primary balancing segment values. The group accountant owns the journal. Local controllers review their own company legs. Agree on that split before anyone edits configuration or hand-tunes generated lines, because fixing things in the wrong place is how small mistakes turn into permanent ones.
Follow Oracle’s Balancing Sequence
Oracle’s documentation on Intercompany Balancing Rules describes the feature as the way to generate the accounts needed to balance journals that are out of balance by legal entity or by primary balancing segment value. The intercompany receivables and payables accounts you configure act as templates, and the feature builds the actual balancing accounts from them.
The order of operations is the part people tend to skip. Oracle explains that journal lines are first summarised and balanced by legal entities. If a legal entity has several primary balancing segment values, the lowest of them is used during that stage, and balancing across the values inside the entity happens afterwards.
That sequence changes how you predict results for this allocation. Don’t guess the generated lines by staring at the largest debit, and don’t assume each entity has just one company value. List every balancing value that appears in the journal for Denmark, Poland and Portugal, and check which legal entity each one belongs to. If an entity carries more than one value, your expected result has to reflect the lowest-value behaviour Oracle documents.
This helps when something looks odd. A surprising line may turn out to be perfectly consistent with the configuration. A line sitting in the wrong legal entity is a different animal: that points to a mapping or input problem, and it deserves a proper investigation rather than a shrug.
Resolve Competing Rules by Precedence in an Oracle Fusion Financials Course
Real setups rarely have just one rule. Oracle documents four levels, in descending order of precedence: primary balancing segment, legal entity, ledger, and chart of accounts. When a more specific level applies, it wins over the ones below it. So the group accountant should inventory candidate rules at all four levels instead of opening only the chart-wide default and assuming that’s the end of the story.
She should also look at the journal source and category. Inside a chart-of-accounts rule, Oracle describes an evaluation order that starts with a specific source and category, moves through combinations that use Other, and finishes with Other source and Other category. Once you know that order, rule selection stops being guesswork and becomes a chain you can test link by link.
Here’s how it might play out. A rule at the primary balancing segment level for the Danish provider could override a legal-entity rule, while a chart-wide rule covers the Polish receiver because nothing more specific applies. The test record should name the rule expected to win and explain why each higher-precedence candidate does or doesn’t apply. Writing that down forces clear thinking, and it gives the next reviewer something to check against.
One more point deserves attention. Oracle cautions that a rule, once created, cannot be modified. It can be end-dated and replaced. So the change plan should respect effective dates and retest journals that fall around the transition. Treating a replacement as an in-place edit is the kind of assumption that surfaces at month-end, when nobody has time for it.
What Oracle Fusion Financials Online Training Should Throw at the Design
A design only earns trust once someone has tried to break it. For this allocation, four negative tests are worth running.
The first changes the journal category while leaving amounts and entities alone. If you only intended the specific source-and-category rule to apply, the result will show which fallback rule steps in instead, and whether that fallback is acceptable.
The second removes coverage for Portugal. This tells you whether the chart-level rule really closes the gap or whether Portugal only worked because of a more specific rule you forgot about.
The third swaps a Polish company value onto the Portuguese journal line. Totals still balance, but the mapping is wrong, and a balanced journal must never be allowed to excuse it.
The fourth uses two balancing values inside Denmark. That lets the reviewer confirm the lowest-value treatment Oracle documents, followed by balancing within the entity.
Then there is the many-to-many case, where more than one provider and more than one receiver sit in the same journal. Oracle’s page says that clearing-company options manage many-to-many balancing, and it recommends setting them to avoid balancing failures during posting or Create Accounting. The available conditions are to use a clearing company for intracompany journals, to use it for all many-to-many journals, or to raise an error when such a journal occurs, which is the default Oracle describes. The team should pick a policy on purpose and test it. A tidy three-entity allocation doesn’t prove that every many-to-many journal will behave.
Reconcile Generated Lines Across Three Views
Reconciliation works best when you look at the same numbers from three angles.
Start at journal level. The original expense and recovery lines must agree with the approved allocation schedule. The generated intercompany lines must then bring each legal entity and each balancing value to the state you expected.
Next, move to counterparty level. Denmark’s receivable, broken down by receiver, should line up with the payables that Poland and Portugal recognise. If Poland shows a payable that Denmark’s receivable doesn’t explain, you have found your problem before it travels any further.
Finally, look at consolidation. Reciprocal positions should be easy to match there. Consolidation is not the place to discover basic coding mistakes, because by then they’re expensive to trace. Whenever a difference turns up, assign it to a cause: allocation, mapping, rule selection, account generation, or timing. A named cause is far easier to fix than a vague variance.
Sign-off evidence should include the approved cost schedule, the journal source and category, the mapping of entities to balancing values, the applicable rule hierarchy, the generated accounts, the effective dates, and the counterparty comparison. Rerun the tests after any replacement rule, chart change, new company value, or altered source-and-category combination.
Two cautions are worth keeping in mind. A journal that posts is not proof that the intended rule won. And equal group-level receivables and payables don’t prove that each Polish or Portuguese counterparty is right. The review stays anchored in the economic story and the expected rule path.
Conclusion
The turbine allocation is under control when the business allocation, legal-entity structure, rule precedence and reciprocal balances all tell the same story. Denmark’s provider position and each receiver’s position should be explainable on their own, not hidden inside a balanced group total.
Deliberate changes to source, category, balancing value and rule coverage show whether fallback paths are truly understood. Oracle Fusion Financials Training, an Oracle Fusion Financials Online Training batch, or an Oracle Fusion Financials Course can build this habit: predict the winning rule, inspect the generated accounts, then reconcile every entity and counterparty before accepting the journal, whatever the scenario.