Introduction
A payment team is preparing a cross-border settlement for a French supplier when generation suddenly stops. Tech Leads IT uses this situation in Oracle Fusion Financials Training to show why a blank bank branch city cannot be fixed by borrowing the supplier’s city. The screen may turn green, but the data would still be untrue.
Oracle Fusion Financials Online Training teaches learners to map every party, repair gaps at the owning record, and rerun validation. A good Oracle Fusion Financials Course also keeps evidence, so the released payment carries accurate address details, not values chosen only to pass a rule.
Oracle Fusion Financials Training Begins With Mapping the Payment Chain
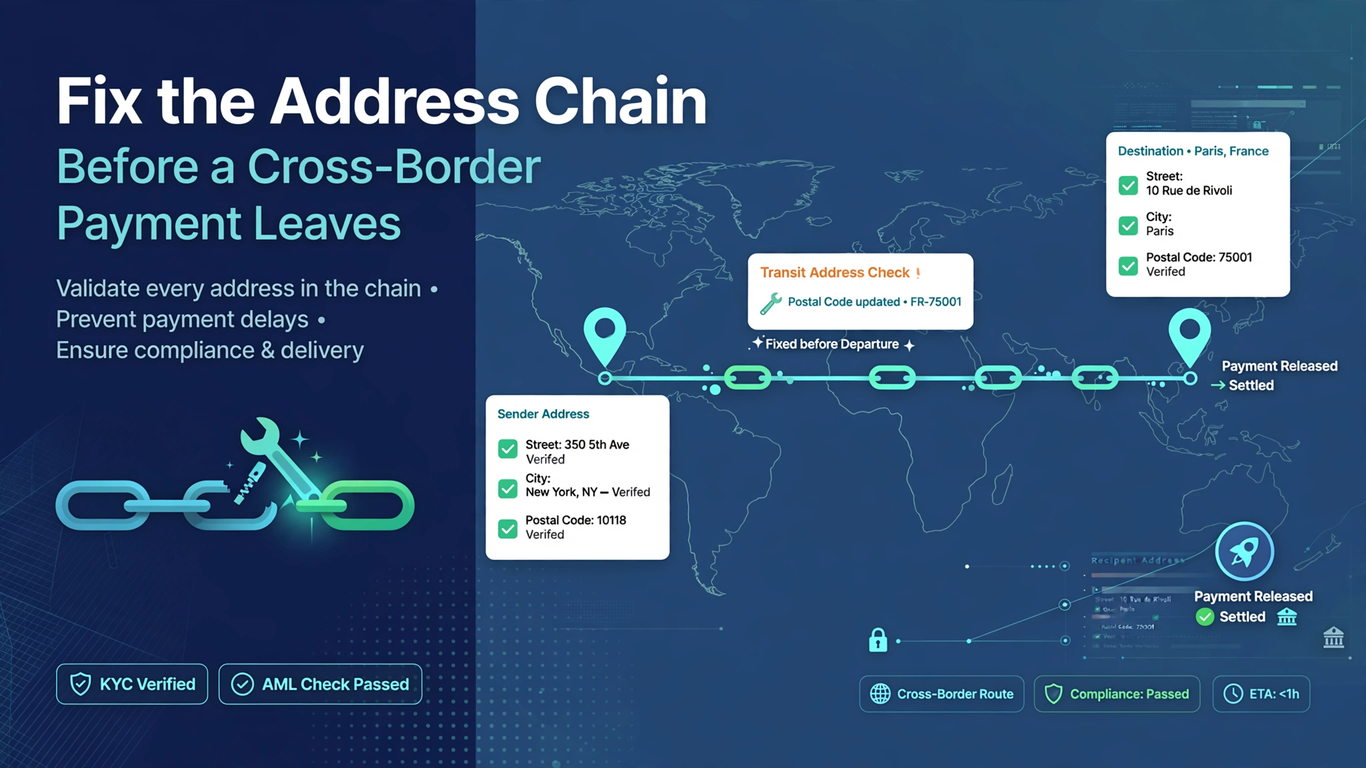
Start with the whole route, not just the supplier. Depending on the payment, the parties can include the payer, payee, ultimate payer, ultimate payee, an intermediary bank, the payer bank branch, and the payee bank branch. Some payments use only part of that chain. Others pick up extra parties through treasury structure or correspondent banking. Build a route record from the payment setup and instruction data, then name the authoritative source for each address. A supplier site may govern the payee address, while a separate bank or branch record governs the financial institution details. Similar street or city values do not make those records interchangeable.
A simple route record might list each party, its role, its country, the record that owns its address, and the person responsible for that record. Even a one-page table like this changes the conversation, because a missing city stops being a vague payment problem and becomes a specific question for a named owner.
For the French supplier, trace the path from the paying legal entity and disbursement account through to the supplier and its bank branch. Note which parties are domestic, which sit across the border, and which address components are filled in today. Done early, this exercise exposes the blank branch city before a live payment request exists. Keep it a data-readiness review, not a collection drive. Limit the inventory to fields the payment process needs, and protect exports under your policy, so you find ownership and gaps without creating an uncontrolled spreadsheet of sensitive payment-party data.
Understand What the Validation Actually Requires
Cross-border payment formats lean more and more on structured postal information. For the applicable parties, town or city name and country code need attention, and the payee bank branch city is required on cross-border payments. Presence is only the first test. Country codes must follow the expected standard, city values must belong to the right party, and the records should reflect verified business information. The validation is not a promise that an address is deliverable, current, or free of other defects. It checks defined conditions during payment generation, and people still have to judge authenticity and context.
Think of it as a gate rather than a guarantee. The gate is useful precisely because it is narrow, and the team’s job is to cover everything it does not check.
Oracle’s Postal Address Validation for Cross-Border Payments documentation explains that these checks run automatically during payment generation, and a failing payment cannot proceed until the missing information is supplied. That boundary is helpful because it stops incomplete instructions before transmission. It also means a late discovery can threaten a cutoff. Set up a readiness report or controlled review ahead of payment day for active foreign suppliers, bank branches, and other applicable parties. Group findings by data owner, not just by payment processor, because a treasury or payables user may see an error without having the authority or evidence to fix the master record behind it.
Oracle Fusion Financials Online Training Should Teach Repairs at the Source
When the branch city is blank, pause the payment and confirm the branch identity through approved documentation or a controlled verification channel. Then update the bank branch record through the governed maintenance process, with maker-checker review where it is required. Do not borrow the supplier’s city, guess a location from the bank name, or paste in a city from an internet search. A bank can serve a supplier through a branch in another city or even another country.
The strongest repair ties the value to evidence, records who changed it and when, and keeps full bank instructions and confidential correspondence out of free-text comments. A reviewer reading the history later should see a verified fact with an owner, not a convenient guess made at four in the afternoon.
Timing matters here too. If branch confirmation takes a day, the honest options are to ask for a cutoff extension or move the payment to the next cycle. Both beat sending an instruction with a made-up city. A late payment has a cost, but a misrepresented bank branch can cost more, and it is much harder to explain afterward.
Align Profiles, Formats, and Templates
Clean data is not enough if the payment configuration follows an older or customized route that never applies the intended artifacts. For integrated business-to-business bank partners, the delivered CBPR+ validation depends on new predefined payment process profiles. Configurations built on earlier profiles or customized templates need review across payment process request templates, profiles, formats, and templates. Inventory each cross-border payment route and document which combination it invokes.
Resist the urge to replace a customized profile blindly. Find out why it was customized, compare the output requirements, and test equivalent changes before promotion. Configuration lineage matters as much as party-data lineage, because a perfect branch record does nothing if the route never reads it the way you expect. A comparison sheet listing the profile, format, and template for each route, along with its owner and last change date, makes later reviews far easier. When a bank asks why a file looked different this month, the team that can name the profile, format, and template involved will answer in minutes instead of days.
Build a Test Matrix Around Realistic Routes
Design the matrix around routes you really run. Include a standard foreign supplier payment, one with an intermediary bank, one with an ultimate payee, and one domestic payment that should not be misclassified. For each case, predict the applicable parties and required values, generate the payment, and inspect both the validation behavior and the resulting structured output through approved tools. A test passes only when valid records proceed and invalid records stop for the expected reason.
Record the expected result before running each case. Writing the prediction first keeps testers from reading the outcome and then deciding it looked right.
If every case passes, go one step further and deliberately remove one required city and one country code. Negative tests prove the validation is active, not merely that clean sample data can flow. They also show the team what a failure looks like before a real cutoff makes it stressful.
Use the Review Stop as a Controlled Queue
When Stop Payments for Review is selected, address failures appear on the Resolve Payment Validation Errors page along with their errors. Treat that page as an exception queue, not a place to improvise data. Give each item an owner, record the failed party and attribute, and link the repair to its approved master-data request. Keep the payment from moving forward until the source is corrected and validation is rerun.
The reviewer should also tell apart several payments blocked by one shared bank branch from several unrelated defects. Fixing the common record may clear the whole group, but every payment still needs its own successful validation result. Age matters in this queue too. Items close to the cutoff should be visible to everyone, so nobody discovers a stuck payment at the last minute.
Retry Only After You Know the Prior State
Design retry controls around the payment process request. Before rerunning, establish whether the failed attempt created any instruction, output, or bank transmission. Use payment identifiers and process status instead of assuming an error message means nothing happened. Rerun only the intended population, and reconcile counts and values before release.
A short checklist before each rerun helps: confirm the repair is approved, confirm no instruction exists from the failed attempt, and confirm the selection covers only the intended payments.
In the scenario, the repaired branch record should let the held French supplier payment advance once, while an intentionally incomplete intermediary-bank case stays stopped. That proves remediation is selective, and that a broad retry neither releases other exceptions nor duplicates payments that already succeeded.
Monitor Readiness Before Cutoff
Keep proportionate evidence of configuration testing, data correction approval, the failed validation, the successful rerun, payment release, and bank acknowledgment. Restrict access, and avoid copying full account information into logs. At closeout, reconcile the approved payment population with generated instructions and transmitted totals.
An address correction changes payment master data, while release moves cash. Those events deserve distinct authorization even when the same operational team coordinates them. A clean audit trail shows who established the correct city, who approved the payment, which validation result cleared it, and which instruction finally reached the bank. It also gives auditors and bank contacts one coherent story instead of a pile of screenshots.
Conclusion: What an Oracle Fusion Financials Course Should Leave Behind
Reliable payment processing starts with an address chain that reflects the real parties and institutions. Oracle Fusion Financials Training should show learners how to map the route, verify city and country data at the right source, and align profiles and formats. Validation failures are controlled work, not obstacles to bypass.
Oracle Fusion Financials Online Training adds one rule: rerun after confirming the repair and the earlier process state, then reconcile the release to the bank acknowledgment. A good Oracle Fusion Financials Course makes one missing branch city visible, because the safe answer is verified data, accountable remediation, and one valid payment.