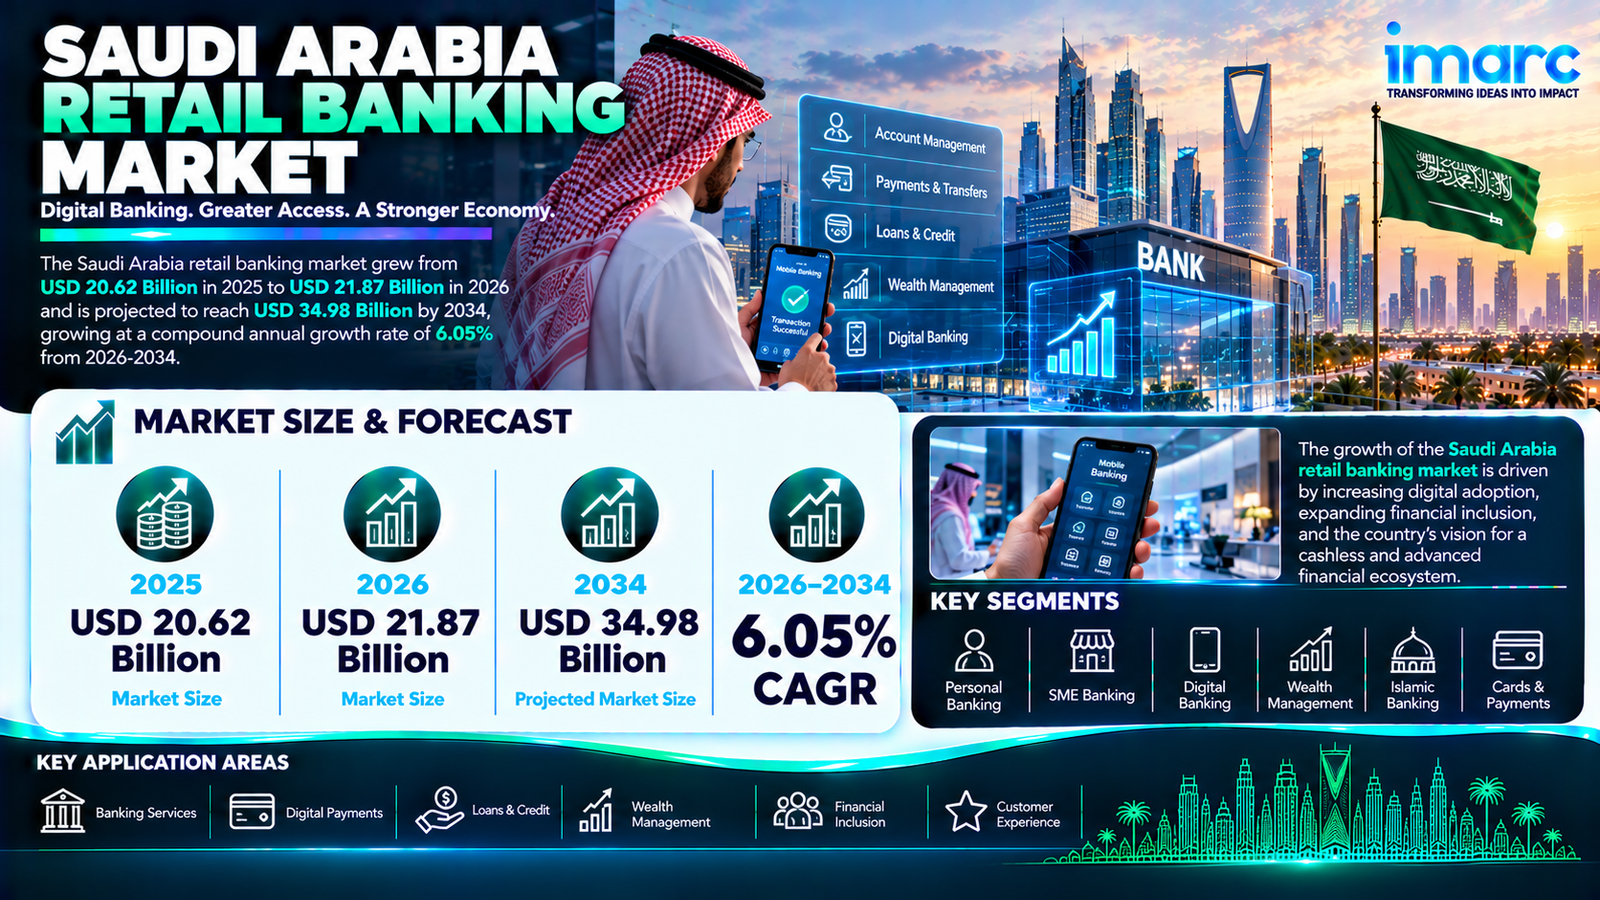
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia retail banking market. The Saudi Arabia retail banking market size increased from USD 20.62 Billion in 2025 to USD 21.87 Billion in 2026 and is projected to reach USD 34.98 Billion by 2034, exhibiting a CAGR of 6.05% during 2026-2034, driven by Vision 2030 financial sector reforms, rising digital banking adoption, and expanding mortgage and personal lending demand across the Kingdom.
The market is riding sustained structural momentum as the Kingdom accelerates its shift from a cash-based economy into a digitally integrated financial system. Debit card adoption, open banking frameworks, and the licensing of digital-only banks are widening the addressable market across retail payments, lending, and wealth advisory services. Riyadh’s position as the Kingdom’s financial and administrative capital keeps the Northern and Central Region the dominant banking hub, while D360 Bank, the Kingdom’s first licensed digital-only bank, and established players such as Al Rajhi Bank and Saudi National Bank anchor a market built for sustained digital transformation rather than a single reform cycle.
Saudi Arabia Retail Banking Market at a Glance:
- Market Size (2025): USD 20.62 Billion
- Market Size (2026): USD 21.87 Billion
- Forecast Market Size (2034): USD 34.98 Billion
- CAGR (2026-2034): 6.05%
- Leading Product (2025): Debit Cards, 20% share
- Leading Channel (2025): Direct Sales, 58% share
- Dominant Region (2025): Northern and Central Region, 28% share
How AI is Reshaping the Future of the Saudi Arabia Retail Banking Market
- AI-Driven Personalization and Digital-Only Banking: Digital-only banks such as D360 Bank are using advanced data analytics and artificial intelligence to deliver personalized financial products and streamlined onboarding, appealing to younger, tech-savvy consumers and pushing traditional banks to accelerate mobile-first strategies.
- AI-Powered Fraud Prevention and Compliance: Riyad Bank’s Center of Intelligence, the Kingdom’s first dedicated artificial intelligence hub in banking, is applying machine learning to improve operational performance, while Mozn’s AI-based anti-money-laundering collaboration with D360 Bank is strengthening digital banking security and regulatory compliance.
- Open Banking APIs and AI-Enabled Financial Ecosystems: Open banking frameworks are enabling secure data sharing between banks and fintechs, allowing AI-driven platforms to build tailored lending, savings, and advisory products and accelerating the pace of innovation across the sector.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-retail-banking-market/requestsample
Saudi Arabia Retail Banking Market Trends and Drivers:
Digital transformation is the single biggest structural shift in the market, with debit cards commanding 20% of the product mix in 2025 as consumers transition toward contactless and mobile wallet-integrated payments. Open banking and fintech collaboration are compounding this shift directly, with electronic payments accounting for 79% of total retail transactions in 2024 and e-commerce transactions using mada cards reaching nearly SAR 29.86 Billion in July 2025, while services remain the backbone of banking activity at 50% share as banks expand account management, lending, and advisory offerings through direct sales channels that capture 58% share via branch networks and digital platforms.
Riyadh’s position as the Kingdom’s financial and administrative capital is a structural, not incidental, advantage. The Northern and Central Region leads the market with a 28% share in 2025, hosting the concentration of major bank headquarters, corporate entities, and government institutions that sustain demand for retail banking services. D360 Bank’s launch in December 2024 as the Kingdom’s first licensed digital-only bank is emerging as the clearest proof point of this digital ambition, drawing strong early customer adoption and prompting established banks to accelerate mobile application upgrades and digital onboarding. These developments are contributing to Saudi Arabia retail banking market growth by strengthening digital banking adoption, expanding customer access to financial services, and intensifying competition among traditional and digital-first banking institutions.
Government-backed reform is the accelerant behind both trends. The Financial Sector Development Program, a cornerstone of Vision 2030, has lifted the share of bank credit to the private sector relative to GDP from 61% in 2023 to 69% in 2024, reaching SAR 2,752 Billion and recording 13% annual growth, while the Sakani housing program has pushed homeownership to 65.4% in 2024, surpassing its original 2025 target. Layered on top, Saudi banks’ total loans and advances grew 13.6% year-on-year in 2024 to reach SAR 4.21 Trillion, with Al Rajhi Bank alone issuing SAR 693.4 Billion, up 16.8%, while the Saudi Real Estate Refinance Company’s USD 2 Billion international sukuk in May 2025 injected fresh liquidity into the mortgage market.
Government Schemes and Vision 2030 Initiatives Driving Demand:
- Financial Sector Development Program (FSDP): Launched under Vision 2030, the FSDP is promoting financial inclusion, innovation, and the sector’s contribution to economic diversification, having lifted the share of bank credit to the private sector relative to GDP from 61% in 2023 to 69% in 2024, reaching SAR 2,752 Billion with 13% annual growth.
- Sakani Housing and Mortgage Program: Government-backed housing initiatives have elevated homeownership to 65.4% in 2024, surpassing the original 2025 target, while the Saudi Real Estate Refinance Company’s USD 2 Billion sukuk issuance in May 2025 has expanded liquidity for mortgage lending.
- Digital Bank Licensing Framework: The Saudi Central Bank’s licensing of digital-only banks enabled D360 Bank to become the Kingdom’s first digital bank to commence operations in December 2024, intensifying competition and accelerating digital product innovation across the sector.
- Open Banking Regulatory Framework: Regulatory reforms enabling secure data sharing between banks and third-party providers are fostering the creation of personalized financial products and supporting a growing fintech ecosystem across the Kingdom.
- SARIE Instant Payment System Expansion: The Saudi Arabian Riyal Interbank Express system is processing billions of real-time transactions annually, pushing digital transactions to represent a significant majority of retail banking activity nationwide.
Saudi Arabia Retail Banking Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Product:
- Transactional Accounts
- Savings Accounts
- Debit Cards
- Credit Cards
- Loans
- Others
Debit cards command the largest product share at 20% in 2025, driven by the Kingdom’s strategic push toward a cashless economy, widespread point-of-sale deployment, and the mada payment network’s role in facilitating secure, seamless transactions across retail and digital commerce channels.
Breakup By Application:
- Hardware
- Software
- Services
Services lead the application segment with a 50% share in 2025, reflecting the fundamental nature of retail banking as a service-oriented industry built on account management, lending facilities, payment processing, and wealth advisory offerings delivered increasingly through digital channels.
Breakup By Channel:
- Direct Sales
- Distributor
Direct sales represent the largest channel segment at 58% share in 2025, as banks deepen customer engagement through branch networks, mobile applications, and dedicated relationship managers while transforming branches from transaction points into advisory hubs for complex financial consultations.
Breakup By Region:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Northern and Central Region dominates the Saudi Arabia retail banking market with a 28% share in 2025, anchored by Riyadh’s concentration of bank headquarters, corporate entities, and government institutions. The Western Region follows, driven by commercial activity, tourism, and religious pilgrimage logistics across Jeddah, Mecca, and Medina, while the Eastern Region’s share reflects its role as the center of the petroleum industry and its sizeable expatriate population, and the Southern Region, though the smallest segment, is gaining ground through government development programs aimed at expanding economic activity and financial access across the Kingdom’s diverse geography.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the Saudi Arabia retail banking market with detailed profiles of all major companies, including:
- Al Rajhi Bank
- Saudi National Bank
- Riyad Bank
- Banque Saudi Fransi
- Alinma Bank
- Bank AlJazira
- Arab National Bank
- D360 Bank
Market Concentration Analysis:
- Fragmentation: Established national banks hold the majority of retail banking revenue, though no single institution commands outright market dominance as digital-only banks and fintechs steadily capture share.
- Consolidation Trend: Strategic partnerships between traditional banks and fintech innovators are accelerating, exemplified by Mozn’s AI-based AML collaboration with D360 Bank and Al Rajhi Bank’s partnership with RATL Technology on its MUHIDE trade-finance platform.
- Capital Inflows: Government-backed capital and fintech investment are reshaping competitive dynamics, with the Saudi Real Estate Refinance Company’s USD 2 Billion sukuk issuance and growing fintech sector activity supporting scale-building across the market.
What Does The Full Report Cover?
If you are tracking the Saudi Arabia retail banking market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group’s report gives you everything in one place:
- Complete market sizing in value terms with forecasts covering the full 2026-2034 projection period
- Quantified growth driver analysis with impact scoring across product, application, channel, and regional markets
- Sub-segment breakdowns for six product categories, three application types, two distribution channels, and all four regions of the Kingdom, each with individual share data
- Regional data across the Northern and Central, Western, Eastern, and Southern regions of Saudi Arabia
- Competitive profiles of leading national banks and digital challengers with strategic landscape assessment
- Value chain analysis, market concentration assessment, and investment and growth opportunity mapping
- Latest technology trends covering AI-driven personalization, digital-only banking, open banking frameworks, and Vision 2030-driven financial sector reforms shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia Retail Banking Market
- March 2025: Mozn partnered with D360 Bank to advance digital banking security through AI-based anti-money-laundering compliance solutions, reinforcing the bank’s focus on secure, customer-centric digital services.
- February 2025: Al Rajhi Bank partnered with RATL Technology to launch the MUHIDE fintech platform for SME trade-finance governance, expanding digital capabilities for business banking customers.
- September 2024: Saudi National Bank introduced its ‘NEO’ digital banking platform, offering personal expense tracking, savings tools, currency conversion, and an integrated digital retail store.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia retail banking market size and what is its projected value?
- Which product holds the largest share in the Saudi Arabia retail banking market?
- What are the key drivers of Saudi Arabia retail banking market growth?
- Which region dominates the Saudi Arabia retail banking market and why?
- How is Vision 2030, the Financial Sector Development Program, and digital banking adoption reshaping competitive strategy in the Saudi Arabia retail banking industry?
- Who are the top companies in the Saudi Arabia retail banking market and what are their competitive strategies?
- What are the investment and market entry opportunities across digital banking, open banking, and mortgage lending in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104