Introduction
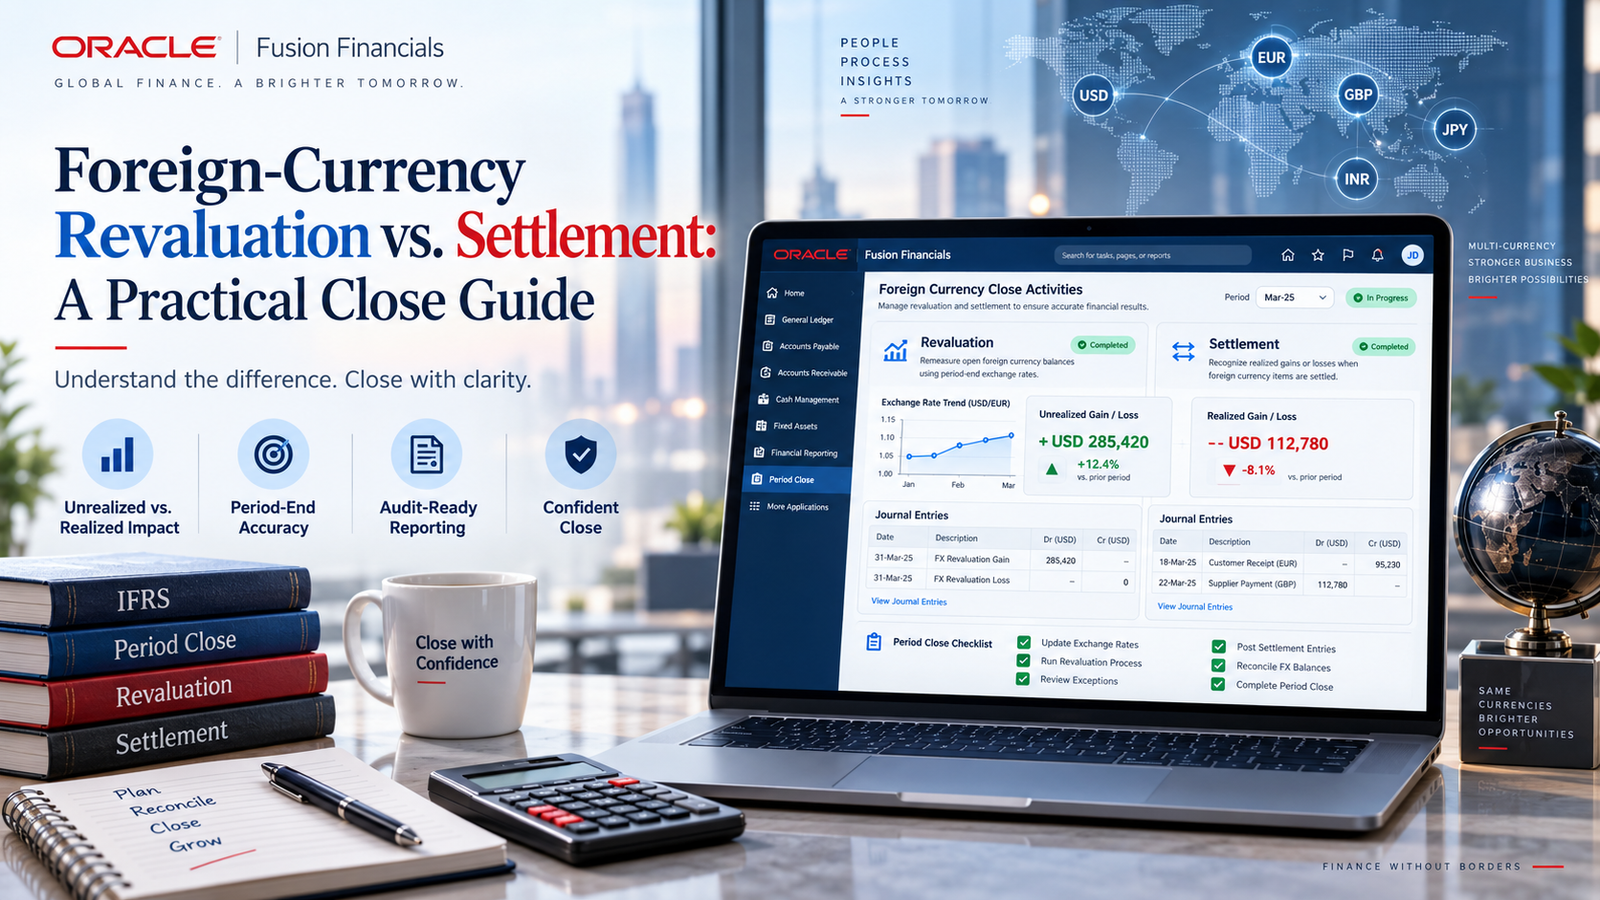
A foreign-currency payable can produce an accounting gain or loss before any cash moves. At Soft Online Training, we see this confuse many teams during month-end close, because the revaluation journal looks like liability activity even though the supplier remains unpaid. The invoice creates the obligation, and period-end revaluation updates its ledger-currency equivalent.
Settlement later clears the obligation at the payment rate. Revaluation only measures exposure at a reporting date; it never changes the invoice currency, renegotiates the supplier amount, or proves payment occurred. Mastering this practical distinction is always a core focus of Oracle Fusion Financials Training in Bangalore.
Why Revaluation Matters in Oracle Fusion Financials Training in Bangalore
Finance professionals joining Oracle Fusion Financials Training in Bangalore quickly find that revaluation is one of the most misunderstood close activities. It is not a mysterious journal that appears at period end. It is a controlled measurement of monetary balances at the closing rate. Learners who grasp this early can explain the numbers to auditors, controllers, and business owners instead of only running the process. Everything below follows one principle: keep measurement and settlement as separate events.
Keep Entered and Accounted Amounts Separate
Suppose an entity records a 100,000-euro liability when one euro equals 1.08 units of ledger currency. The entered amount stays at 100,000 euros. If the closing rate rises to 1.11, the ledger-currency value of the obligation increases. Revaluation changes the accounted representation, not the contractual units owed.
Reviewers should keep four facts distinct: the foreign amount, the original accounted amount, the closing rate, and the resulting adjustment. Merging them into one balance makes it hard to tell whether a movement came from new transactions, payments, rate changes, or corrections.
Account selection matters too. Receivables, payables, foreign-currency cash, and other monetary accounts often have different owners and reconciliation evidence. A broad account range may pull in balances that policy never intended to revalue, or it may miss a newly created account that it should include. Map the definition to the chart of accounts and document exclusions. Before running the process, reconcile entered-currency balances to the subledger or supporting schedule, so revaluation does not lend false precision to a flawed base population.
Treat Exchange Rates as Controlled Inputs
The closing rate must follow the organization’s accounting policy for the currency and reporting date. Confirm the rate type, date, source, load status, and approval. A rate can exist in the system and still be wrong if it belongs to a different rate type or was loaded for the wrong date. For currencies affected by holidays or thin markets, document how the applicable rate was chosen. Never silence a missing-rate warning by typing in a convenient value. The journal may post cleanly while the valuation basis stays indefensible.
Test reciprocal rates and decimal precision as well, since an inversion error can create a large but plausible-looking adjustment. Compare the proposed rate with the previous close and investigate significant movement before posting. This is not a forecast of where exchange rates should go. It is a control over the input and its direction. When several ledgers share a market source, confirm that each local calendar and policy still supports the chosen date, rather than assuming one centrally loaded rate suits every entity.
What the Revaluation Journal Does: Lessons from Oracle Fusion Financials Training in Bangalore
The Oracle Help Center’s revaluation documentation explains that the process adjusts foreign-currency balances for conversion-rate changes between the original journal date and the revaluation date. The adjustment is posted to the underlying account, with an offset to an unrealized gain or loss account. This is the central point trainers stress in Oracle Fusion Financials Training in Bangalore: the journal updates the carrying amount and recognizes an unrealized result, but it does not clear the original item. Review the underlying account and the offset together, and avoid reading the gain or loss line as an isolated performance figure.
Configuration affects presentation. When the same account is used for unrealized gains and losses, Oracle derives and posts the net adjustment. Separate accounts preserve directional visibility, while a shared account emphasizes the net result. Choose the setup that matches reporting policy and management needs. Also inspect the balancing segments and other dimensions in the generated journal. A correct total posted to the wrong company or cost center can distort local results even when the consolidated figure looks reasonable.
Plan the Reversal Before You Post
For balance-sheet accounts, Oracle documents that revaluation journals are reversed in the next period, and AutoReverse can automate this. Reversal stops the prior closing adjustment from staying embedded when the next period’s valuation is calculated and when settlement happens. Include reversal period, date, method, and status in the close checklist. A September revaluation posted without its October reversal can cause the next analysis to blame current activity for an old adjustment, or distort the realized result when the payable is finally settled.
Not every revaluation journal is reversed. Oracle distinguishes income-statement accounts using the period-to-date method, where journals are not reversed because each adjustment applies only to its own period. Account classification and method therefore become review evidence. Do not copy a blanket reversal assumption from monetary balance-sheet accounts. Define the expected treatment by account group, then compare generated journals and scheduled reversals against that expectation before closing the period.
Use the Execution Report as Audit Evidence
The process automatically produces a Revaluation Execution report. According to Oracle, it lists the currencies and rates used, the unrealized gain or loss account, the account range, the batch and journal names created, and total debits and credits. Keep this report with close support and tie its batches to posted journal totals. Review coverage currency by currency instead of trusting an overall balanced entry. The report bridges configuration and result, showing which inputs and scope produced the accounting in the ledger.
Warnings deserve resolution, not informal acceptance. If the process cannot find rates for one or more currencies, Oracle states that those balances are not revalued and the report lists the missing rates. A journal can therefore be balanced, posted, and still incomplete. Identify every warning, quantify the excluded exposure, correct the approved rate data, and rerun the process or document an authorized disposition. Confirm that a rerun does not duplicate adjustments already posted, and that the retained report matches the journal batch used for reporting.
Explain the Movement Through a Rollforward
A useful rollforward starts with the prior entered and accounted balances. It then adds new foreign-currency activity, subtracts settlements and other clearings, identifies corrections, and finally shows the current revaluation adjustment. Keep realized effects, which arise at settlement, apart from unrealized effects, which arise at the reporting date.
For large movements, explain whether the driver was exposure volume, currency direction, or both. This prevents a favorable unrealized result from being presented as operational performance. It also helps management notice a growing currency position even when the period’s net gain or loss is small.
Conclusion: Building Close Confidence with Oracle Fusion Financials Training in Bangalore
Revaluation is a controlled reporting-date measurement, not a black-box close entry. Reviewers must establish the entered-currency population, validate rates and account scope, understand the unrealized offset, confirm reversal treatment, and resolve every execution warning. Settlement remains a separate event with its own cash movement and realized effect.
Structured Oracle Fusion Financials Training in Bangalore helps finance teams build exactly this discipline, from configuring revaluation to defending the results at close. When the execution report, journal, reversal, and rollforward all agree, finance can explain what the entity still owes or holds in foreign currency and why its ledger-currency value changed, without implying that any counterparty was paid.