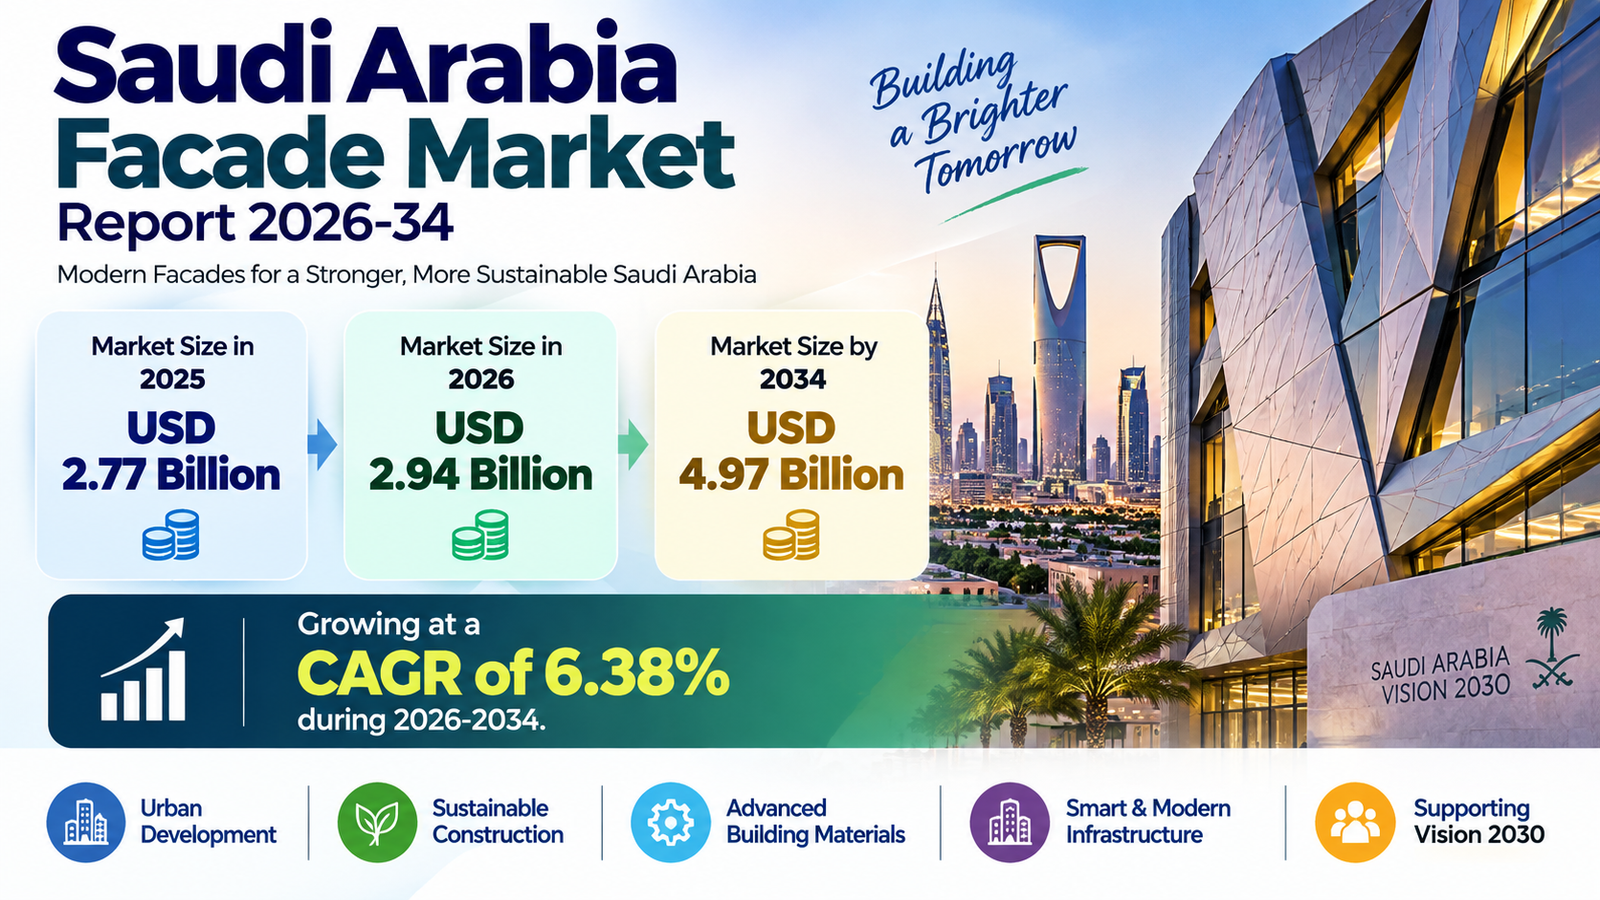
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia facade market grew from USD 2.77 Billion in 2025 to USD 2.94 Billion in 2026 and is projected to reach USD 4.97 Billion by 2034, exhibiting a CAGR of 6.38% during 2026-2034, driven by rapid urbanization, ambitious giga-project construction activity under Vision 2030, stringent building codes promoting energy efficiency, and growing demand for aesthetically distinctive, sustainable building exteriors across the Kingdom’s commercial and residential landscape.
The market is experiencing strong growth momentum as Saudi Arabia’s construction sector undergoes a structural transformation, with facade systems shifting from a purely protective building element to a defining architectural and performance statement. Riyadh, Jeddah, and NEOM are emerging as the epicenters of demand, with developers increasingly specifying kinetic facades, smart glass, and custom aluminum systems to meet both aesthetic ambitions and extreme climatic performance requirements. Annual giga-project contract awards in Saudi Arabia surged 20% to reach USD 196 Billion, underscoring the scale of capital flowing into developments that rely heavily on advanced facade engineering. NEOM’s The Line alone features approximately 2.1 million square meters of mirrored glass facade planned across its first phase, illustrating the magnitude of opportunity within a single giga-project.
How AI is Reshaping the Future of the Saudi Arabia Facade Market?
- AI-Driven Facade Performance Simulation and Energy Modeling: Building information modeling platforms integrated with AI algorithms are enabling architects and facade contractors to simulate thermal loads, solar heat gain, and structural stress across different facade materials before construction begins, allowing developers to optimize glazing ratios, shading systems, and insulation specifications for Saudi Arabia’s extreme desert climate while reducing costly design revisions during the construction phase.
- Computer Vision for Quality Inspection on Prefabricated Facade Lines: As modular and prefabricated facade panels become the norm for giga-projects, AI-powered computer vision systems are being deployed on production lines to detect surface defects, panel misalignment, and sealing inconsistencies at high throughput, helping manufacturers meet the tight delivery schedules required by mega-developments such as NEOM, The Red Sea Project, and Qiddiya.
- Predictive Maintenance and Smart Glass Automation: AI-enabled sensors embedded within electrochromic and thermochromic smart glass facades are allowing building operators to automatically adjust transparency and shading based on real-time sunlight intensity and occupancy patterns, while predictive maintenance algorithms flag potential seal failures or mechanical faults in kinetic facade systems before they escalate into costly repairs.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-facade-market/requestsample
Saudi Arabia Facade Market Trends and Drivers
The Saudi Arabia facade market is witnessing sustained expansion, propelled by the convergence of Vision 2030 megaproject investment, evolving building regulations, and a national push toward energy-efficient, climate-responsive architecture. The construction pipeline across the Kingdom is estimated to include over USD 800 Billion worth of contracts over the coming years, with a significant proportion involving advanced glazing, curtain walling, and ventilated facade systems. On the western seaboard alone, 17 giga-projects including NEOM, The Red Sea Project, and Qiddiya Coast are underway, with contracts worth USD 57 Billion already awarded and a further USD 187 Billion in the pipeline, according to property consultancy Knight Frank. Riyadh has emerged as a particular hotspot, accounting for 63% of all new jobs created in the Kingdom since 2019, with the city’s population projected to expand from 7 million toward 10.1 million, alongside plans for more than 340,000 new homes, 4.8 million square meters of office space, and 3 million square meters of retail space, all of which will require substantial facade installation.
Energy efficiency regulation is emerging as a central driver reshaping product specification across the market. Updated design guidelines introduced in January 2025 place greater emphasis on sustainability and energy performance, pushing developers toward double-glazed units, Low-E coatings, and solar-control glass that can deliver energy savings of up to 20% in well-designed structures. Saudi Arabia’s national population, which continues to grow at an annual rate of approximately 1.5%, is intensifying demand for modern residential and commercial infrastructure, particularly in expanding metropolitan hubs. Extreme climatic conditions across the Kingdom, marked by intense solar radiation and high ambient temperatures, are simultaneously pushing manufacturers to innovate in thermally optimized materials, reinforcing demand for facades engineered specifically for desert performance rather than adapted from temperate-climate designs.
Prefabrication and modular construction are becoming the dominant delivery model for large-scale facade installation, driven by the need for precision engineering, reduced material waste, and faster project completion on tight giga-project deadlines. Both local and international facade suppliers are expanding their prefabrication capacity to serve the Kingdom’s construction boom, with modular systems offering the design flexibility required for high-rise buildings and complex architectural forms. This trend is reinforced by government efforts to modernize construction practices through digitalization and industrialization, including procurement portals that connect international suppliers with giga-project developers seeking specialized facade expertise.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=32149&flag=E
Saudi Arabia Facade Industry Segmentation
The report has segmented the market into the following categories:
Breakup By Product Type:
- Ventilated
- Non-Ventilated
- Others
Ventilated facade systems account for a leading share of the product type segment, favored for their ability to create an air cavity between the building structure and outer cladding that improves thermal insulation and moisture control, a performance advantage that is particularly valuable given the Kingdom’s extreme heat and the growing regulatory emphasis on energy-efficient building envelopes.
Breakup By Material:
- Glass
- Metal
- Plastic and Fiber
- Stones
- Others
Glass remains a dominant material segment, driven by its widespread use in curtain walling for commercial towers and mixed-use developments, where architects favor glazed facades for their ability to maximize natural daylight, deliver striking visual statements, and integrate smart glass technologies such as electrochromic and thermochromic coatings that automatically regulate solar transparency.
Breakup By End Use:
- Commercial
- Residential
- Industrial
The commercial segment leads the end use category, supported by the sheer scale of office towers, hospitality developments, retail complexes, and mixed-use giga-project components under construction across Riyadh, Jeddah, and NEOM, where facade specification is treated as a core element of brand identity and architectural distinction rather than a purely functional building component.
Breakup By Region:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Central Region, anchored by Riyadh, commands a substantial share of the market, driven by projects such as King Abdullah Financial District and King Salman Park, which spans over 1 million square meters, alongside the broader wave of residential and commercial construction supporting the capital’s rapidly expanding population.
Competitive Landscape
The report provides a comprehensive analysis of the competitive landscape in the Saudi Arabia facade market with detailed profiles of key companies operating across curtain wall fabrication, glazing systems, and architectural cladding, including regional and international players engaged in design, manufacturing, and installation of ventilated and non-ventilated facade solutions for the Kingdom’s commercial and residential construction sectors.
What Does The Full Report Cover?
If you are tracking the Saudi Arabia facade market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group’s report gives you everything in one place:
- Complete market sizing with revenue estimates and outlook
- Quantified growth driver analysis with impact scoring across product type, material, end use, and regional markets
- Sub-segment breakdowns for ventilated, non-ventilated, glass, metal, plastic and fiber, stone, commercial, residential, and industrial categories with individual share data
- Regional data for the Northern and Central, Western, Eastern, and Southern regions of Saudi Arabia
- Competitive profiles of leading facade companies with strategic landscape assessment
- Porter’s Five Forces, value chain analysis, and pricing intelligence
- Latest product innovation trends covering smart glass, kinetic facades, modular and prefabricated systems, and energy-efficient glazing technologies shaping market competition
Recent News and Developments in Saudi Arabia Facade Market
- December 2025: Industry research highlighted that Saudi Arabia’s facade sector is set for sustained expansion, with the Red Sea Project and other giga-projects prioritizing modular and prefabricated facade systems to achieve cost and time efficiency, as off-site manufacturing and digital construction practices gain traction across the Kingdom.
- October 2025: Knight Frank reported that construction contracts worth USD 24 Billion have been awarded for the NEOM project and its sub-projects, including USD 8.9 Billion for The Line and USD 9.3 Billion for Oxagon, developments that carry substantial facade and curtain wall scope.
- July 2025: New Murabba Company signed an agreement with Korea-based Heerim Architects and Planners to collaborate on architectural overlays for its 19 square kilometer mixed-use development in Riyadh, with the company separately inviting interest from contractors for large-scale design-build facade development packages.
- May 2025: Market research highlighted that Saudi Arabia’s glass curtain wall segment is benefiting from an expanding construction boom, with over 300,000 housing units planned and glass curtain wall systems increasingly specified for their ability to deliver energy savings of up to 20% in well-designed structures.
- January 2025: Updated national design guidelines emphasizing sustainability and energy performance came into effect, a regulatory shift expected to shape facade material and system choices across upcoming commercial and residential developments in the Kingdom.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia facade market size and what is its projected value?
- Which product type segment holds the largest share in the Saudi Arabia facade market?
- What are the key drivers of Saudi Arabia facade market growth?
- Which region dominates the Saudi Arabia facade market and why?
- How are Vision 2030 sustainability goals, energy efficiency regulations, and giga-project investment reshaping product development and competitive strategies in the facade industry?
- Who are the top companies in the Saudi Arabia facade market and what are their competitive strategies?
- What are the investment and market entry opportunities across ventilated, glass, commercial, and prefabricated facade segments?
About Us
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104